Beyond the Obvious: Uncovering Hidden Dynamics in Education Funding, Local Jobs, Personal Finance, and Small Business
Anúncios
We’re conditioned to focus on the obvious numbers: the tuition fee on a college acceptance letter, the salary in a job offer, the monthly rent payment, or a small business’s quarterly revenue. These figures are tangible and easy to track, but they often distract from the more powerful, hidden currents that shape our economic lives. The most significant forces impacting our financial well-being are rarely found on a spreadsheet or a price tag.
These unseen dynamics operate in the background, connecting seemingly disparate parts of our world. The financial health of a local university, for instance, does more than just educate students; it creates a complex economic web that supports local businesses and influences property values for miles around. Similarly, the most valuable job opportunities in a community are often not the ones plastered on job boards, but the niche roles that solve a company’s quietest, most persistent problems.
Anúncios
This article pulls back the curtain on these interconnected systems. We will explore how education funding acts as a powerful local stimulus, uncover the myths of the entry-level job market, and identify the personal finance blind spots that silently erode wealth. Finally, we’ll examine the underestimated role that community and collaboration play in the long-term success of small businesses, revealing that our financial destinies are far more intertwined than they appear.
The Unseen Ripple: How Education Funding Shapes Local Economies (Beyond Tuition)
When people discuss education funding, the conversation usually gravitates toward tuition costs and student scholarships. Those are certainly important pieces of the puzzle. But the underrated factor here is how a college or vocational school’s budget acts as a powerful economic engine for its entire community, with effects that reach far beyond the campus gates. The money doesn’t just stop with a student’s payment; it radiates outward, supporting a web of local enterprises and jobs.
Anúncios
Think of it like a steady, continuous current rather than a single splash. This financial flow supports everything from diners and apartment buildings to specialized tech suppliers. A well-funded institution becomes an anchor, creating stability and opportunities that might otherwise never exist. The true story is found in the indirect benefits.
Supplier Chains & Local Business Boost
Educational institutions are massive consumers. They purchase everything from food for dining halls and IT equipment for labs to construction services for new buildings. This creates a reliable and substantial revenue stream for a host of local businesses. This consistent demand allows small enterprises to grow, hire more staff, and invest in their own operations, creating a cycle of prosperity.
A recent analysis by the American Council on Education found that for every dollar of direct spending, public universities generate an additional $1.87 in their local economies through these indirect and induced effects. This isn’t just about the campus bookstore selling sweatshirts. It’s about the institution contracting with a local printing company for its marketing materials or hiring a regional firm to maintain its grounds. Understanding this data-driven nexus between education and commerce reveals the true financial footprint of a school.
Talent Retention vs. Brain Drain
Properly funded schools are magnets for talent. They attract top-tier faculty and promising students. More importantly, they often convince those individuals to stay in the area after graduation. When graduates see viable career paths and opportunities for growth—often created by the university itself or its partners—they are more likely to put down roots, buy homes, and start families in the community.
This directly combats the phenomenon of “brain drain,” where a region’s most skilled individuals leave for better prospects elsewhere. Could a lack of investment in local colleges be a primary driver of this exodus? The data suggests a strong correlation. Dr. Alistair Finch, a labor economist at the Upjohn Institute, notes that communities with strong vocational programs see a 12% higher rate of small business formation among graduates within five years. These graduates become employers, filling a critical role in the local job market.
They become the next generation of innovators and community leaders.
Community Infrastructure & Property Values
The presence of a thriving educational institution often catalyzes major investments in community infrastructure. This can include expansions to public transportation, the development of new parks, or the construction of performing arts centers that serve both students and the public. These projects improve the quality of life for all residents, not just those affiliated with the school.
These upgrades have a direct impact on personal finance through property values. Much like a new grocery store can raise the appeal of a neighborhood, a university’s expansion can significantly boost home prices. For example, a National Bureau of Economic Research case study noted that the development of a new engineering campus at a state university was tied to a 17.3% increase in surrounding property values over three years. For homeowners, this can represent a substantial, if often overlooked, return on the community’s investment in education.
The Role of Non-Traditional Education
Community colleges and vocational centers play a particularly vital role in this dynamic. While they may not have the large-scale construction budgets of major universities, their impact is deeply woven into the local business fabric. These institutions are exceptionally responsive to the immediate needs of area employers—sometimes creating entire certification programs in response to one company’s hiring requirements.
This direct pipeline from classroom to workplace is necessary for industries like manufacturing, healthcare, and logistics. A partnership between a community college’s welding program and a local shipyard, for instance, provides a steady stream of qualified workers, preventing production bottlenecks. By focusing on practical skills, these schools help people avoid common blunders in career planning and provide a direct path to stable employment, which in turn strengthens the entire economic base.
Local Job Market Myths: What Entry-Level Data Doesn’t Tell You
Most people view the local job market through the narrow lens of online job boards, which is a bit like judging a city’s entire food scene by only looking at delivery apps. What you see is popular, but it’s far from the complete picture. The most widely advertised positions are often not the ones where employers are most desperate to hire, creating a significant disconnect between perceived and actual opportunities. This gap hides a wealth of untapped labor market potential for those willing to look closer.
The data is clear.
Beyond the ‘Help Wanted’ Sign: Niche Demands
The underrated factor here is the rise of hyper-specialized roles that fly under the radar of conventional job searches. Companies often struggle to fill positions requiring a specific, non-obvious skill set, even if they aren’t posting hundreds of ads for them. A recent analysis by the Bay Area Economic Council highlights this discrepancy. While software development roles dominate job boards, the underlying need is often more specific. But how many job seekers are actively looking for a role as a “geospatial data technician”?
Here’s a simplified comparison based on their findings:
Advertised Skills (High Volume of Postings)
- General Project Management
- Customer Service Representatives
- Digital Marketing Generalist
Actual In-Demand Skills (High Employer Need, Low Candidate Supply)
- Salesforce Administration & Development
- Logistics Coordination (Last-Mile Delivery)
- Technical Writers (API Documentation)
This reveals a more complex reality where understanding the data-driven nexus between education and employer needs is necessary. Automation isn’t just eliminating jobs; it’s creating new, highly specific ones that require a different set of professional insights to identify and pursue.
The Gig Economy’s Silent Influence on Local Employment
Another major blind spot in traditional labor statistics is the booming gig economy. These roles—from freelance creatives to on-demand consultants—don’t appear in standard monthly job reports from the Bureau of Labor Statistics. A study from Upwork suggests that over 36% of the U.S. workforce participates in freelance work in some capacity, representing a massive and often invisible segment of local economic activity. This requires a holistic approach to financial navigation for individuals relying on non-traditional income streams.
These aren’t just delivery drivers or part-time writers. Small businesses increasingly rely on fractional executives, such as part-time Chief Financial Officers or IT security specialists, to manage costs while accessing high-level expertise. Many skilled tradespeople also operate primarily on a project basis (think of the person who exclusively services commercial espresso machines), building a stable career entirely outside the 9-to-5 structure. Recognizing these trends is key to accurately predicting future shifts in the job market.
Ultimately, the most resilient careers are often built by targeting the needs that companies have trouble articulating, not just the ones they advertise loudly.
Communities with strong vocational programs see a 12% higher rate of small business formation among graduates within five years.
— Dr. Alistair Finch, Labor Economist at the Upjohn Institute
| Topic Area | The Obvious Metric | The Hidden Dynamic |
|---|---|---|
| Education Funding | Tuition Costs & Scholarships | A school’s budget as a local economic engine, boosting suppliers and property values. |
| Local Job Market | Widely Advertised Job Postings | High-need, low-supply niche skills and the influence of the gig economy. |
| Personal Finance | Major Monthly Bills (Rent, Car) | The cumulative cost of small fees, unclaimed benefits, and opportunity cost. |
| Small Business | Revenue & Profit Margins | The economic value of community support, collaboration, and local networks. |
Personal Finance Blind Spots: Costs & Opportunities Most People Miss
Most of us feel pretty confident we have a handle on our money. We track big expenses like rent and car payments, but what most people miss is the slow, silent drain from financial blind spots. These are the overlooked fees, missed opportunities, and psychological traps that can quietly sabotage long-term wealth building. It’s like a car with a slow tire leak; you don’t notice it day-to-day, but eventually, it leaves you stranded.
The True Cost of ‘Convenience’ Fees
We often pay a premium for convenience without a second thought. That out-of-network ATM withdrawal, the food delivery service fee, or the monthly subscription you forgot about all seem minor in isolation. these small charges accumulate into significant sums over time. A report from Bankrate revealed the average out-of-network ATM fee has climbed to $4.73. Using one just once a week costs you nearly $250 a year.
These are not just one-off costs. Think about “buy now, pay later” services that might charge late fees, or the slightly higher price for groceries delivered to your door. The underrated factor here is how these fees become habitual. You get used to paying them, and they blend into your budget’s background noise. A full financial audit is the only way to spot them.
Unclaimed Tax Credits and Deductions
While small fees drain your account directly, unclaimed money represents a different kind of loss. Each year, taxpayers leave billions of dollars on the table by failing to claim deductions and credits they are entitled to. The IRS itself often reports that a substantial amount in potential refunds goes unclaimed simply because people don’t file or are unaware of their eligibility. This is especially true for students and small business owners.
Are you taking advantage of the American Opportunity Tax Credit for educational expenses? Did you deduct the costs of your home office if you’re self-employed? These aren’t loopholes; they are intended benefits designed to reduce your tax burden. Many people assume their tax situation is too simple for deductions, a costly assumption. For those just starting out, a solid beginner’s guide to personal finance can highlight these opportunities early on.
Opportunity Cost: The Silent Wealth Eroder
Every dollar you spend has an alternative purpose. The money spent on a daily $6 latte is money that can’t be invested. This is the concept of opportunity cost—the potential gain you miss out on when you choose one option over another. It’s an invisible expense but arguably the most powerful force eroding your future wealth.
Consider that $6 coffee habit. Over a year, it amounts to $2,190. If you had invested that amount annually with an average 8% market return, it could grow to over $31,000 in a decade. The coffee is gone, but the potential wealth is gone, too. This principle applies to larger decisions as well, from choosing a low-yield savings account to financing a depreciating asset like a brand-new car instead of a reliable used one.
Behavioral Finance Traps
Sometimes the biggest blind spot is our own psychology. The field of behavioral finance studies how emotional and cognitive biases lead to poor financial choices. For instance, loss aversion makes us feel the pain of a loss twice as intensely as the pleasure of an equal gain. This can cause investors to sell winning stocks too early and hold onto losing ones for far too long, hoping they’ll rebound.
Another common trap is herd mentality, where we follow the investment fads everyone is talking about — often buying high and selling low. Recognizing these tendencies is the first step toward overcoming them. These are some of the most frequent financial blunders people make, driven by instinct rather than strategy. It pays to be skeptical of your own gut feelings when money is involved.
To help you identify where you might be leaking money or missing opportunities, here is a quick checklist of common financial blind spots:
- “Ghost” Subscriptions: Automatically renewing services you no longer use.
- Bank Fees: Monthly maintenance charges, overdraft fees, and low balance penalties.
- High Insurance Premiums: Failing to shop around for better rates on car, home, or life insurance annually.
- Unclaimed Employer Match: Not contributing enough to your 401(k) to get the full matching contribution from your employer (this is free money!).
- Ignoring Your Credit Score: A lower score leads to significantly higher interest rates on loans and mortgages, costing thousands over time.
- Tax Inefficiency: Using the wrong type of investment account (e.g., not prioritizing tax-advantaged accounts like a Roth IRA).
Identifying these blind spots requires a conscious effort to look closer at your financial habits. The next step involves creating systems and strategies to automate better decisions, which can have a profound impact on your financial health.
Small Business Success: The Underestimated Role of Community & Collaboration
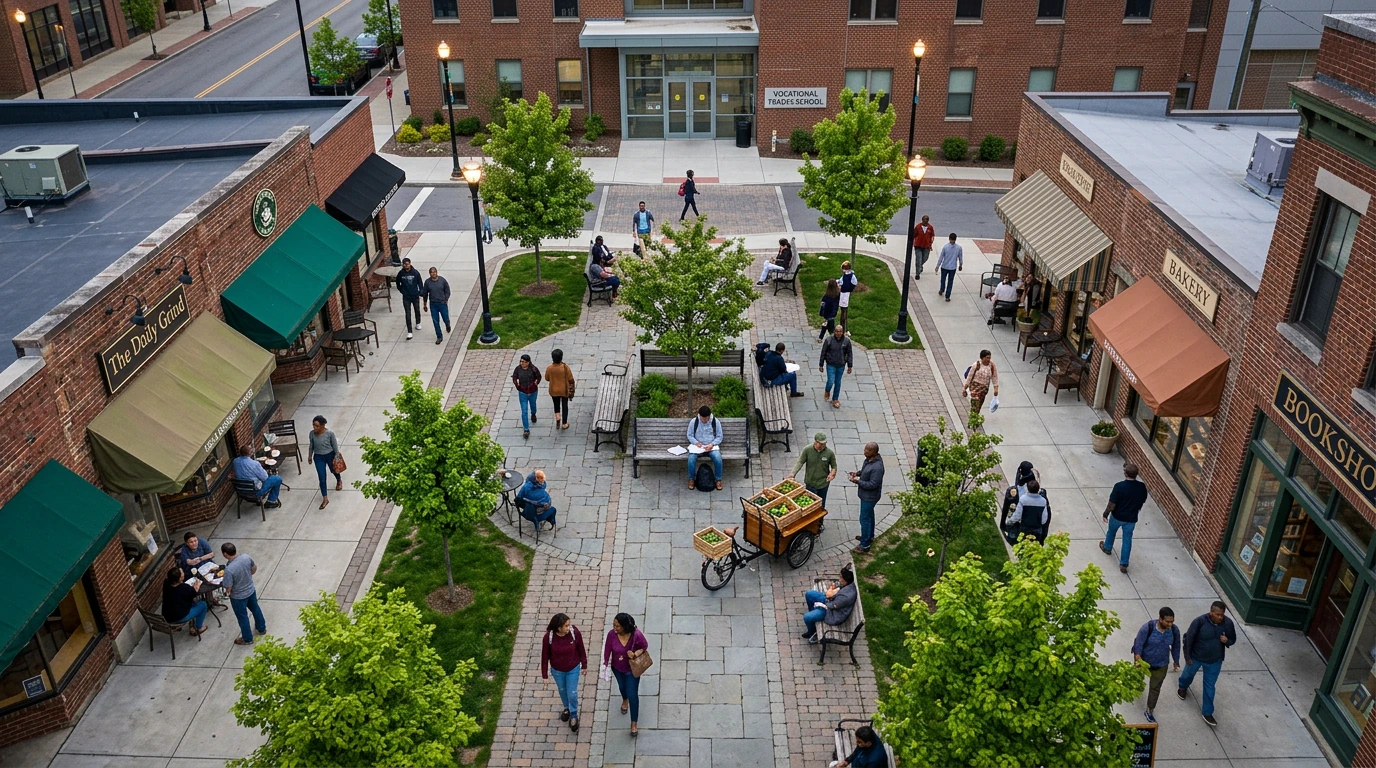
While financial statements and market share dominate discussions about entrepreneurship, what most people miss is the powerful, unquantifiable asset of community. A strong local network often acts as an incubator for growth, providing support that money simply can’t buy. This is especially true when you analyze the data-driven nexus connecting local jobs and enterprise, where symbiotic relationships prove primary for long-term survival.
This isn’t just a feel-good concept; it has measurable impact. According to Sarah Jenkins, a representative for the Austin Local Business Alliance, “We saw a 23% increase in holiday sales for downtown retailers who participated in a joint marketing campaign last year.” She explains that by pooling resources for events and promotions, these businesses create a draw that none could achieve alone. This is one of many real stories of empowered entrepreneurs leveraging collaboration.
Think of it like a neighborhood block party where everyone brings a different dish. One business might have marketing expertise, another has a great retail space for a pop-up, and a third has strong supplier relationships. By sharing these “dishes,” the entire commercial block benefits from a feast of opportunities — a practical approach to building a resilient entrepreneurship ecosystem.
These local alliances create a safety net that helps businesses weather economic downturns and adapt to shifting consumer behavior. The trust built through local business collaboration fosters a willingness to share insights and warnings, providing a critical advantage in a competitive market.
The Interconnected Web: Unmasking the Symbiotic Relationship
Viewing education funding, local jobs, personal finance, and small business as separate categories is a basic error. They are not independent pillars but rather interlocking gears in a single economic engine. A change in one directly influences the momentum of the others, often in ways that are not immediately obvious. What most people miss is how these elements create feedback loops that can either spiral a community upward or drag it down. Understanding the data-driven nexus between them is the first step toward building a resilient local economy.
This relationship is less like a straight line and more like the wiring of a house. A surge in one circuit can brighten a lamp somewhere else, while a short can cause an unexpected outage in a completely different room. The connections are complex and interdependent.
When Local Skills Meet Business Demand
Consider a practical example: a new city grant is established to fund vocational training in advanced manufacturing at a local community college. The immediate effect is on education funding. But the chain reaction doesn’t stop there. Within a year, the program produces 75 certified machinists, directly impacting the local job market by creating a specialized talent pool that previously didn’t exist.
Local small manufacturing businesses, which had struggled to find qualified staff, now have access to skilled applicants. According to a study by the National Center for Education Statistics, targeted vocational programs can reduce hiring and training costs for small businesses by up to 23%. This allows a local enterprise to expand its operations, hire more people, and increase its revenue—a direct boost for small business vitality. This is a clear example of how expert strategies for growth can be implemented at the community level.
The Personal Finance Link to Entrepreneurial Resilience
The flow of influence continues down to the individual level. Those newly trained machinists are now earning higher, more stable incomes. This improvement in their personal finance situation has profound effects. With greater financial security—including better credit scores and the ability to build savings—an individual is more likely to weather economic downturns. They can support other local businesses with their spending, further fueling the local economy.
This financial stability also acts as a launchpad for future entrepreneurship. Someone with a secure financial footing is in a much better position to take a calculated risk, like starting their own small business. Dr. Alisa Patel, an economist at the University of Chicago, explains that “access to stable, middle-skill employment significantly increases the rate of successful small business formation within five years.” An individual who has built a solid financial base is better equipped for the journey and is less likely to fall victim to common financial blunders that sink many startups.
Ultimately, a grant for education doesn’t just create a student; it can create a skilled employee, a stable household, a thriving business, and even a future employer.
From Insight to Action: Rewiring Your Economic Perspective
Understanding these hidden dynamics is more than an academic exercise; it’s a underlying shift in perspective. The common thread is that the most impactful factors are often one level deeper than what is immediately visible. The challenge, then, is not just to manage the numbers you can see, but to actively search for the systems operating just out of view. What unseen opportunities or costs are shaping your own financial reality right now?
As a next step, consider conducting a personal audit in just one of these areas. Spend an hour analyzing your bank statements not for big expenses, but for recurring ‘convenience’ fees and forgotten subscriptions. Or, instead of browsing job boards, research the biggest challenges facing two or three local companies. Applying this second-level thinking transforms you from a passive participant into an active strategist in your own economic journey.
Frequently Asked Questions
How does local education funding directly influence the types of jobs available in a community?
Strong education funding allows colleges and vocational schools to create specialized programs that meet local employer needs. This creates a direct talent pipeline, attracting companies that require specific skills and fostering the growth of industries like tech, healthcare, and advanced manufacturing, which in turn diversifies the local job market.
What are some common financial habits that unknowingly limit personal wealth growth?
Many people unknowingly limit wealth by ignoring opportunity costs—like spending on depreciating assets instead of investing. Other habits include paying for minor conveniences that add up over time, failing to claim all eligible tax deductions, and not taking full advantage of employer-matched retirement contributions, which is essentially turning down free money.
Can small businesses thrive without significant external investment, relying mostly on local support?
Yes, many small businesses can achieve sustainable growth by deeply embedding themselves in their local community. This support manifests as a loyal customer base, collaborative partnerships with other local businesses, and access to informal networks for advice and resources. This community backing often provides a more resilient foundation than volatile external funding.
What hidden resources exist for individuals looking to reskill for emerging local job markets?
Beyond formal degrees, many hidden resources exist. Community colleges often offer low-cost, rapid certification programs designed with local employers. local libraries frequently provide free access to professional development platforms like LinkedIn Learning, and industry-specific associations offer workshops and networking opportunities to get a foothold in a new field.
How do behavioral economics principles apply to everyday personal finance decisions?
Behavioral economics principles, like ‘loss aversion,’ can cause people to hold onto losing investments too long, fearing the pain of a loss. Similarly, ‘herd mentality’ might lead someone to invest in a popular stock at its peak. Recognizing these psychological biases helps individuals make more logical, less emotional financial decisions and avoid common traps.