College Savings Accounts 2026: Maximizing Tax Advantages & Early Planning Tips
Anúncios
College Savings Accounts 2026: Maximizing Tax Advantages and 5 Tips for Early Planning
The dream of a college education for your children is a common aspiration, but the escalating costs can often feel daunting. As we look towards 2026 and beyond, understanding the landscape of college savings accounts, particularly how to maximize their tax advantages and implement effective early planning strategies, becomes paramount. This comprehensive guide will illuminate the path to securing your child’s educational future, ensuring you’re well-equipped to navigate the financial complexities.
Anúncios
The Rising Tide of College Costs: Why Early Planning for College Savings 2026 is Crucial
It’s no secret that college tuition and associated expenses have been on a relentless upward trajectory. Year after year, the price tag for a four-year degree continues to climb, often outpacing inflation and wage growth. This reality underscores the critical importance of starting to save early. Procrastination is the enemy of prosperity when it comes to education funding. By understanding the projected costs for 2026 and beyond, families can set realistic savings goals and leverage the power of compound interest, a financial marvel that allows your money to grow exponentially over time.
Consider this: a child born today will likely be entering college around 2044. While 2026 might seem far off for some, for others with children approaching college age, it’s just around the corner. The decisions you make now regarding your college savings 2026 strategy will have a profound impact on the financial burden your family faces. Early planning isn’t just about accumulating funds; it’s about strategically positioning those funds to take advantage of every available benefit, especially tax advantages.
Anúncios
Understanding the Landscape of College Savings Accounts
When it comes to saving for college, a variety of accounts offer different benefits and drawbacks. However, one type consistently stands out for its robust tax advantages: the 529 plan. While other options like Coverdell Education Savings Accounts (ESAs) and custodial accounts (UGMA/UTMA) exist, 529 plans generally offer the most comprehensive and flexible benefits for college savings.
529 Plans: The Cornerstone of College Savings 2026
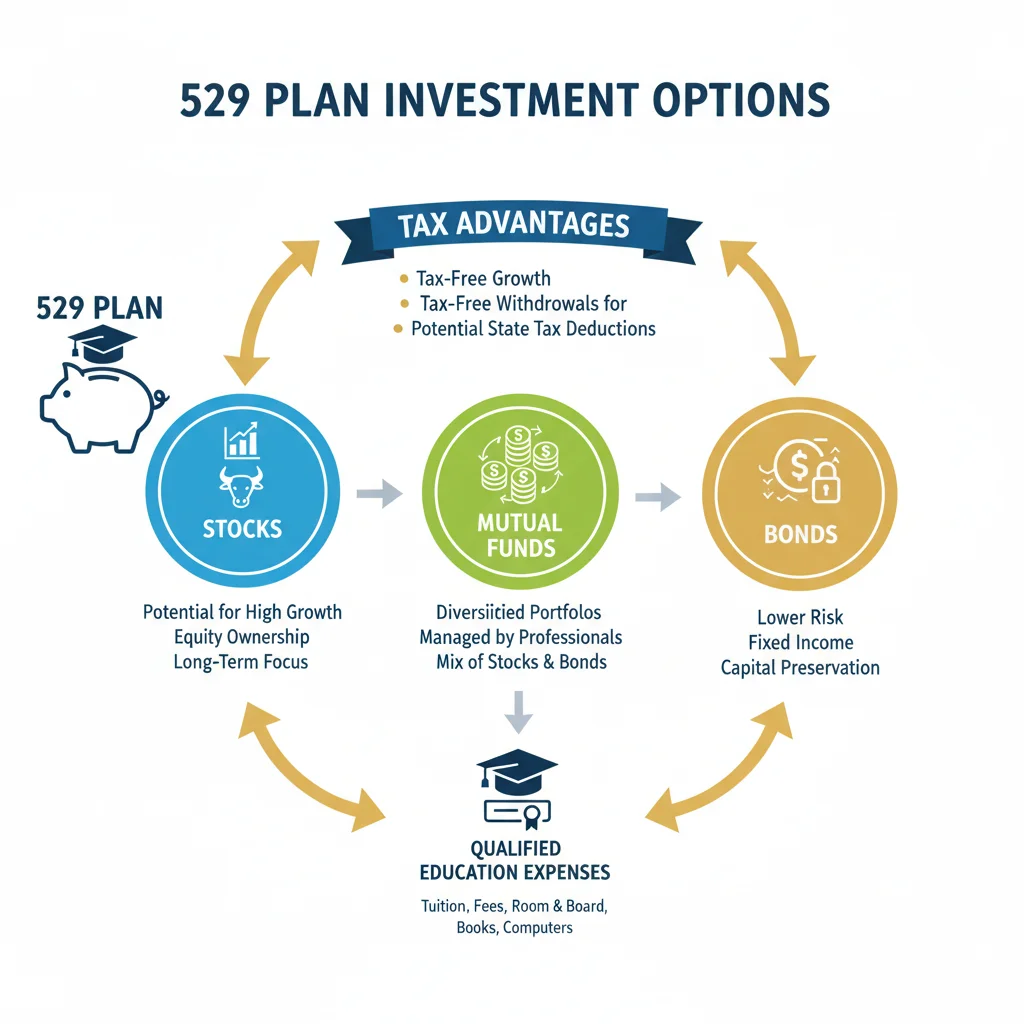
A 529 plan is a tax-advantaged savings plan designed to encourage saving for future education costs. Sponsored by states, state agencies, or educational institutions, these plans come in two main forms: prepaid tuition plans and education savings plans.
- Education Savings Plans: These are the more common type, allowing you to invest contributions in a variety of mutual funds, exchange-traded funds (ETFs), and other investment vehicles. The earnings grow tax-deferred, and withdrawals are tax-free when used for qualified education expenses.
- Prepaid Tuition Plans: These plans allow you to purchase future tuition credits at today’s prices, locking in tuition rates at participating colleges and universities. They primarily cover tuition and mandatory fees, not room and board or books.
For most families planning for college savings 2026, the education savings plan version of a 529 is the more versatile and widely applicable choice, offering greater flexibility in investment options and use of funds.
Key Tax Advantages of 529 Plans for College Savings 2026
The primary appeal of 529 plans lies in their significant tax benefits. These advantages can substantially boost your savings over the long term:
- Tax-Free Growth: This is arguably the most powerful benefit. Your investments within a 529 plan grow tax-free. Unlike a traditional brokerage account where you might pay capital gains tax on earnings each year, a 529 allows your money to compound without federal tax drag, leading to a much larger nest egg.
- Tax-Free Withdrawals for Qualified Expenses: When it’s time to pay for college, withdrawals from a 529 plan are entirely federal income tax-free, provided they are used for qualified education expenses. These expenses include tuition, fees, books, supplies, equipment, and even room and board for students enrolled at least half-time.
- State Income Tax Benefits: Many states offer additional tax benefits for residents who contribute to their state’s 529 plan, or sometimes even to any state’s plan. These can include tax deductions or credits for contributions. Researching your state’s specific 529 plan benefits is a crucial step in maximizing your college savings 2026.
- Estate and Gift Tax Benefits: Contributions to a 529 plan are considered completed gifts for federal gift tax purposes. You can contribute up to $18,000 per year (for 2024, subject to annual adjustments) per beneficiary without incurring gift tax. Furthermore, there’s a special provision allowing you to contribute up to five years’ worth of gifts at once ($90,000 for 2024) without triggering gift tax, provided no other gifts are made to the same beneficiary during that five-year period. This can be a powerful tool for grandparents or wealthy individuals looking to reduce their taxable estate.
- No Income Limitations: Unlike some other education savings vehicles (like Roth IRAs or Coverdell ESAs), there are no income limitations for contributing to a 529 plan. This makes them accessible to families across all income brackets.
Other College Savings Options (and why 529s often win)
- Coverdell ESAs: Offer tax-free growth and withdrawals for qualified education expenses, similar to 529s. However, they have income limitations for contributors, lower annual contribution limits ($2,000 per beneficiary), and funds must be used by the time the beneficiary turns 30.
- Custodial Accounts (UGMA/UTMA): These allow you to gift assets to a minor, but the assets are considered the child’s property for financial aid purposes and are subject to capital gains tax. Once the child reaches the age of majority (18 or 21, depending on the state), they gain full control of the funds, which may not align with your intentions for college funding.
- Roth IRAs: While primarily retirement accounts, Roth IRA contributions (but not earnings) can be withdrawn tax-free and penalty-free for qualified higher education expenses. Earnings can also be withdrawn tax-free if the account has been open for five years and the account holder is over 59½ or meets other exceptions. However, using retirement savings for college can jeopardize your own financial security.
For most families, the superior contribution limits, flexibility, and robust tax advantages make 529 plans the go-to choice for college savings 2026 and beyond.
5 Tips for Early Planning and Maximizing Your College Savings in 2026
Strategic planning is the bedrock of successful college funding. Here are five essential tips to help you maximize your college savings 2026 efforts:
1. Start Early, Even with Small Amounts
The power of compound interest cannot be overstated. The earlier you begin saving, the more time your money has to grow. Even seemingly small, consistent contributions can accumulate into a substantial sum over 10, 15, or 20 years. Don’t wait until you have a large sum to invest; start today, even if it’s just $25 or $50 a month. The magic of compounding is your greatest ally in achieving your college savings 2026 goals.
For instance, investing $100 per month from birth could yield significantly more than investing $200 per month starting when your child is 10. The time in the market is often more important than timing the market or even the size of initial contributions. Make saving a regular habit, perhaps by setting up automatic transfers from your checking account into your 529 plan.
2. Choose the Right 529 Plan and Investment Strategy
Not all 529 plans are created equal. While you’re not restricted to your home state’s plan, it’s wise to first investigate if your state offers any specific tax benefits for its residents. Beyond that, compare plans based on:
- Investment Options: Look for plans that offer a diverse range of underlying investments, including age-based portfolios (which automatically adjust asset allocation as your child approaches college age) and static portfolios.
- Fees: High fees can erode your returns over time. Compare expense ratios of the underlying funds and any administrative fees charged by the plan.
- Performance: While past performance is no guarantee of future results, consistent strong performance is a positive indicator.
- Customer Service and Ease of Use: A user-friendly interface and responsive customer support can make managing your account much easier.
Once you’ve selected a plan, choose an investment strategy that aligns with your risk tolerance and your child’s age. Younger children can typically tolerate more aggressive portfolios (higher stock allocation), while those closer to college age should transition to more conservative investments (higher bond or cash allocation) to protect accumulated gains. Many 529 plans offer age-based portfolios that automate this process for you, making it a simple choice for college savings 2026.
3. Explore All Contribution Avenues
Saving for college doesn’t have to be solely your responsibility. Encourage family and friends to contribute to your child’s 529 plan instead of traditional gifts for birthdays and holidays. Many 529 plans offer easy online gifting platforms. Grandparents, in particular, can be excellent contributors, as their contributions have favorable treatment for financial aid purposes (more on that below) and can also help with their own estate planning.
Additionally, consider redirecting unexpected windfalls, such as tax refunds, bonuses, or inheritances, directly into your college savings 2026 fund. Every extra dollar contributed benefits from the tax advantages and compounding growth.
4. Understand the Impact on Financial Aid
While saving for college is crucial, it’s also important to understand how your savings might affect your child’s eligibility for need-based financial aid. Generally, assets held in a parent-owned 529 plan are treated favorably. Only a small percentage (typically 5.64%) of parental assets are counted in the Expected Family Contribution (EFC) calculation on the Free Application for Federal Student Aid (FAFSA).
Assets held in a student’s name (like UGMA/UTMA accounts) are assessed at a much higher rate (20%). Grandparent-owned 529 plans generally do not count as an asset on the FAFSA, but withdrawals from these plans are considered untaxed student income in subsequent FAFSA years, which can significantly reduce aid eligibility. A strategic approach for grandparents might be to wait until the student’s junior or senior year of college to make withdrawals, as FAFSA uses prior-prior year income, meaning these withdrawals would not impact aid eligibility for the remaining college years.
Staying informed about financial aid rules and how different savings vehicles are assessed is a key component of effective college savings 2026 planning.
5. Regularly Review and Adjust Your Plan
Your college savings 2026 plan shouldn’t be a set-it-and-forget-it endeavor. Life changes, investment markets fluctuate, and college costs continue to evolve. It’s essential to review your plan annually, or at least every few years, to ensure it remains on track. Consider these points during your review:
- Contribution Amounts: Can you increase your contributions as your income grows?
- Investment Allocation: Is your portfolio still appropriate for your child’s age and your risk tolerance? Rebalance if necessary.
- College Cost Projections: Are the projected costs you’re saving for still accurate? Adjust your goals if estimates have changed.
- Plan Performance: How is your chosen 529 plan performing compared to its benchmarks and other plans?
- Changes in Tax Law: Stay informed about any potential changes to federal or state tax laws that might impact 529 plans or other education savings vehicles.
Regular adjustments ensure your college savings 2026 strategy remains optimized and responsive to changing circumstances.
Beyond 529s: Other Considerations for College Funding
While 529 plans are excellent, a holistic approach to college funding often involves considering other avenues:
Scholarships and Grants
These are “free money” that doesn’t need to be repaid. Encourage your child to excel academically and engage in extracurricular activities to boost their chances of securing scholarships. Many scholarships are merit-based, while others are need-based or tied to specific talents, interests, or demographics. Start researching scholarship opportunities early in high school.
Student Loans (as a last resort)
Federal student loans generally offer more favorable terms (fixed interest rates, income-driven repayment plans, potential for forgiveness) than private loans. However, the goal of robust college savings 2026 is to minimize the need for loans, thereby reducing post-graduation debt burden.
Community College First
Attending a community college for the first year or two can significantly reduce overall costs, especially if the credits are transferable to a four-year institution. This can be a smart financial move for families looking to stretch their college savings further.
Work-Study Programs
Federal work-study programs allow students to earn money to help pay for educational expenses through part-time jobs, often on campus. These programs provide valuable work experience without interfering too heavily with academic commitments.
The Future of College Savings: What to Expect Towards 2026
As we approach 2026, the landscape of college savings may see minor adjustments, though the core benefits of 529 plans are expected to remain intact. Potential changes could include:
- Increased Contribution Limits: Annual gift tax exclusion limits (which indirectly affect how much you can contribute to a 529 without triggering gift tax reporting) are typically adjusted for inflation.
- Expanded Qualified Expenses: There’s always a possibility that Congress could expand the definition of qualified education expenses to include more items, although this is less common.
- State-Level Innovations: Some states may introduce new incentives or plan features to make their 529 offerings more attractive.
- Investment Trends: The underlying investment options within 529 plans will continue to evolve, reflecting broader market trends and the availability of new investment vehicles.
Staying informed through reliable financial news sources and consulting with a financial advisor will ensure your college savings 2026 strategy remains current and effective.
Conclusion: Empowering Your Child’s Educational Journey
Saving for college is a marathon, not a sprint. By understanding the powerful tax advantages of 529 plans and diligently applying early planning strategies, you can significantly reduce the financial stress associated with higher education. Starting early, choosing the right plan, diversifying contributions, understanding financial aid implications, and regularly reviewing your strategy are the pillars of successful college savings 2026. Empower your child’s future by making informed financial decisions today, paving the way for a bright and debt-minimized educational journey.
Remember, the best time to plant a tree was 20 years ago. The second best time is now. Apply this wisdom to your college savings plan, and watch your efforts blossom into a robust educational fund for your loved ones.